Finance
Poland gross to net salary 2026: ZUS, health contribution and PIT step by step
On a Polish employment contract your employer deducts social contributions and an income tax advance from your gross pay in a fixed order, and the result is the net amount that reaches your account. This guide follows that order for PLN 6,000 gross, then shows what the PIT-2 form, tax-deductible costs, the under-26 relief and PPK change, and why net pay can shift during the year on a high salary.
- HNarzędzia editorial team
- Published:
Polish job offers and payslips use two words for the same salary: brutto (gross, before deductions) and netto (net, what you receive). Net pay is calculated from gross in five steps, and the order matters. Social contributions reduce the base for the health contribution and the base for income tax, while the health contribution itself does not reduce tax. For PLN 6,000 gross this gives PLN 4,420.43 net. The Polish salary calculator runs these steps for an employment contract (umowa o pracę) and shows the result for every month of 2026. Below you can check where each amount comes from.
The order of deductions
- Employee social contributions are calculated on the gross salary: pension 9.76%, disability 1.5% and sickness 2.45%, 13.71% in total. They are paid to ZUS (Zakład Ubezpieczeń Społecznych), the state social insurance institution, so on a payslip you will see them as “ZUS”. The Social Insurance System Act splits the pension contribution (19.52%) equally between employee and employer. Of the disability contribution (8%) the employee pays 1.5% and the employer 6.5%. The sickness contribution is paid by the employee. The calculator rounds each contribution to the grosz.
- The health contribution (składka zdrowotna) is 9% of gross pay minus the social contributions. Since 2022 you cannot deduct it from income tax: the provision that allowed it has been repealed in the Personal Income Tax Act.
- The tax base is gross pay minus social contributions minus the monthly tax-deductible costs (koszty uzyskania przychodu, KUP): PLN 250, or PLN 300 if you live outside the town where your workplace is and do not receive a separation allowance. The calculator rounds the base to whole zloty.
- The income tax advance (zaliczka na PIT) is 12% of the base minus PLN 300. That PLN 300 is one twelfth of the annual tax-reducing amount (PLN 3,600, which is 12% of the PLN 30,000 tax-free allowance) and your employer applies it only if you have given them a PIT-2 form. The result is rounded to whole zloty. Once your tax base since January exceeds PLN 120,000, the excess is taxed at 32%.
- Net pay is gross pay minus social contributions, health contribution and the tax advance. If you take part in PPK, your own contribution is deducted as well.
Example: PLN 6,000 gross in January 2026
Calculator defaults: costs of PLN 250, PIT-2 filed, no under-26 relief, no PPK.
| Item | Calculation | Amount |
|---|---|---|
| Pension | 6,000 × 9.76% | PLN 585.60 |
| Disability | 6,000 × 1.5% | PLN 90.00 |
| Sickness | 6,000 × 2.45% | PLN 147.00 |
| Social contributions total | PLN 822.60 | |
| Health contribution | (6,000 - 822.60) × 9% = 465.966 | PLN 465.97 |
| Tax base | 6,000 - 822.60 - 250 = 4,927.40, rounded | PLN 4,927 |
| Income tax advance | 4,927 × 12% - 300 = 291.24, rounded | PLN 291 |
| Net pay | 6,000 - 822.60 - 465.97 - 291 | PLN 4,420.43 |
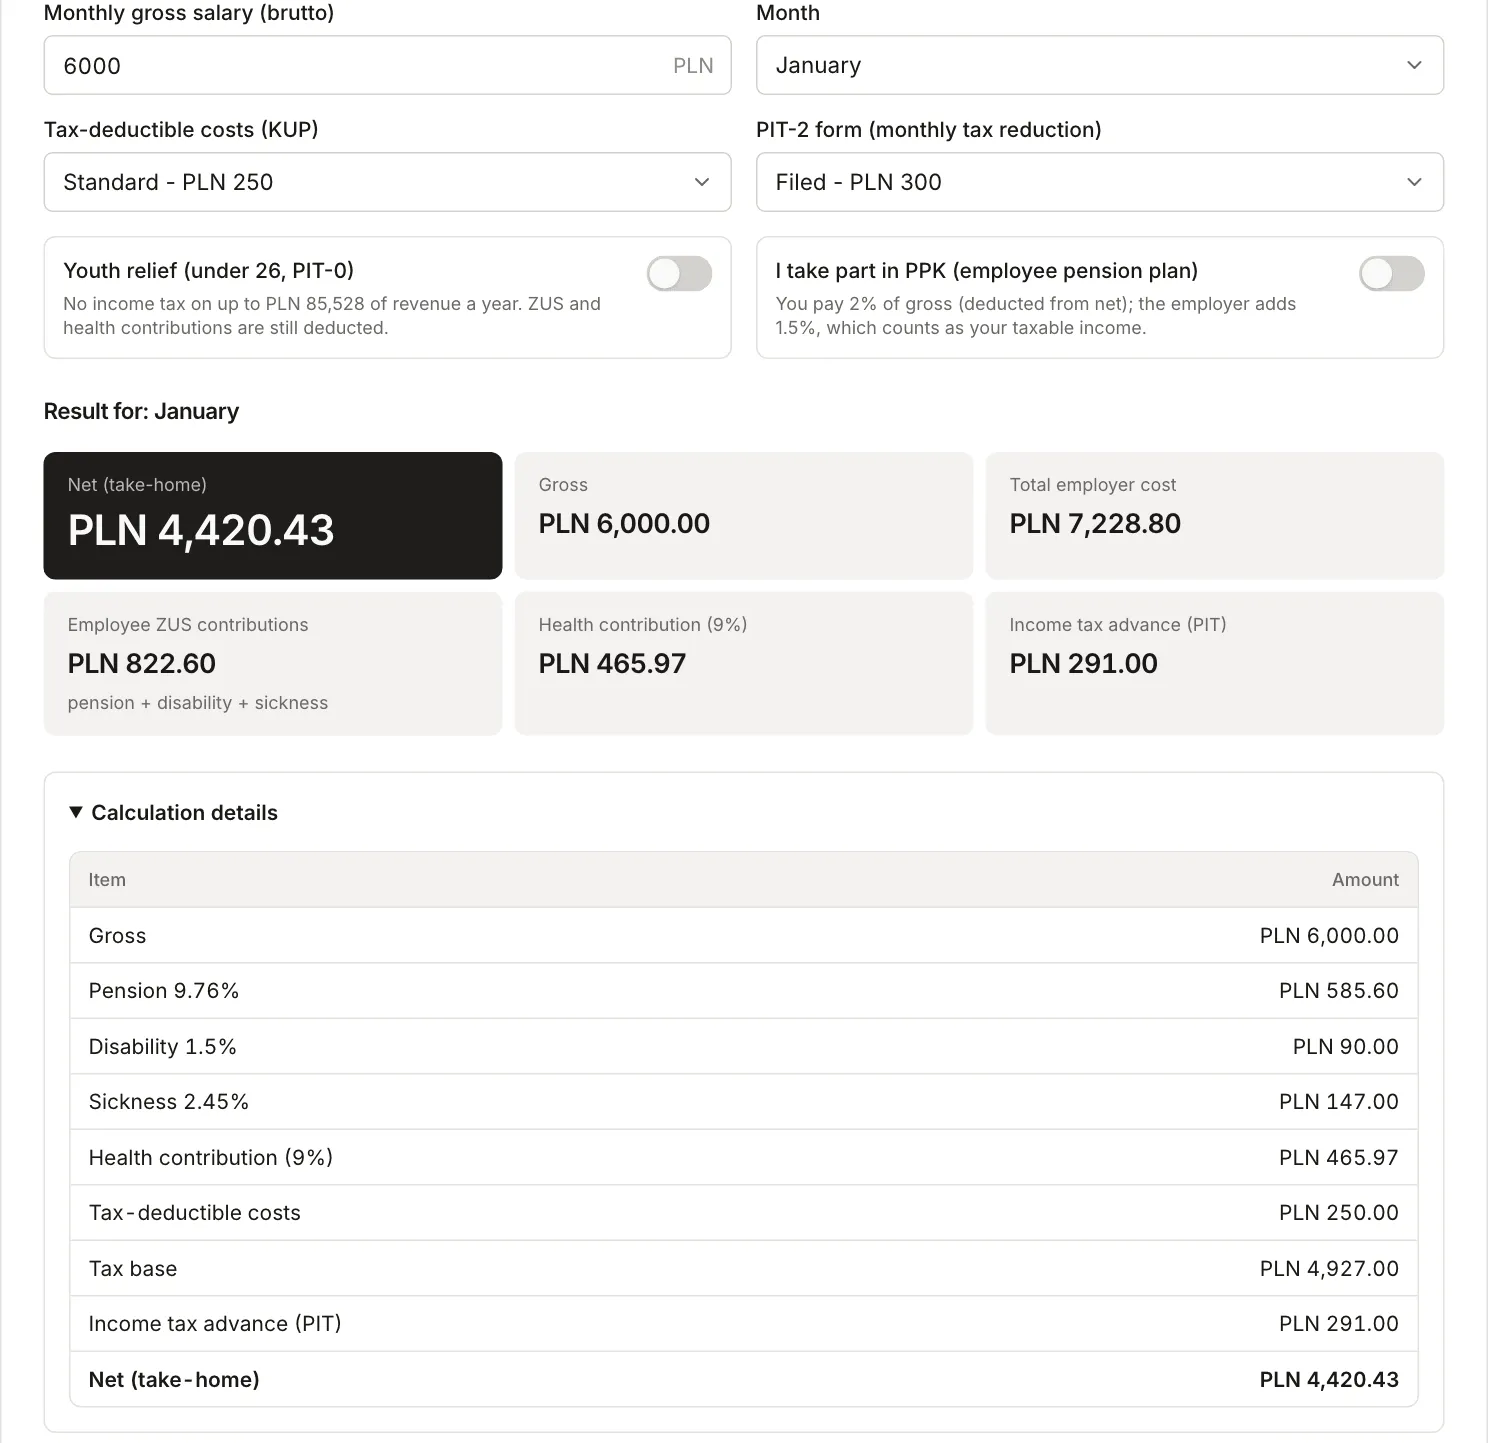
The calculator also shows the total cost to the employer (PLN 7,228.80) separately. It does not affect your take-home pay.
Four gross amounts side by side
January 2026, default settings. The first amount is the minimum monthly wage from 1 January 2026 (Council of Ministers regulation of 11 September 2025, § 1).
| Gross | Social contributions | Health | Tax advance | Net | Net as share of gross |
|---|---|---|---|---|---|
| PLN 4,806 | PLN 658.91 | PLN 373.24 | PLN 168.00 | PLN 3,605.85 | 75.0% |
| PLN 6,000 | PLN 822.60 | PLN 465.97 | PLN 291.00 | PLN 4,420.43 | 73.7% |
| PLN 10,000 | PLN 1,371.00 | PLN 776.61 | PLN 705.00 | PLN 7,147.39 | 71.5% |
| PLN 25,000 | PLN 3,427.50 | PLN 1,941.53 | PLN 2,259.00 | PLN 17,371.97 | 69.5% |
Contributions grow in proportion to pay, and tax takes a growing share of gross, from 3.5% to 9.0%. The fixed PLN 300 reduction and the fixed PLN 250 costs matter less on a higher salary.
What changes the result
The amounts below are for PLN 6,000 gross in January. One setting is changed, everything else stays at the default.
| Setting | Tax advance | Net | Difference |
|---|---|---|---|
| Default (costs PLN 250, PIT-2 filed) | PLN 291 | PLN 4,420.43 | |
| PIT-2 filed with two employers (PLN 150 each) | PLN 441 | PLN 4,270.43 | -PLN 150.00 |
| No PIT-2 | PLN 591 | PLN 4,120.43 | -PLN 300.00 |
| Increased costs (PLN 300) | PLN 285 | PLN 4,426.43 | +PLN 6.00 |
| Under-26 relief | PLN 0 | PLN 4,711.43 | +PLN 291.00 |
| PPK | PLN 302 | PLN 4,289.43 | -PLN 131.00 |
PIT-2
PIT-2 is a short statement you give your employer, normally when you start a job, that lets them reduce your monthly tax advance by the tax-reducing amount. You can give it to at most three payers: one deducts PLN 300, two deduct PLN 150 each, three deduct PLN 100 each (article 31b of the PIT Act). Without it your employer does not reduce the advance, so you receive PLN 300 less every month. The calculator covers only the monthly advances and does not simulate the annual tax return.
Increased costs
PLN 300 instead of PLN 250 lowers the tax base by PLN 50, which is PLN 6 less tax a month. The condition and the statement you give your employer come from article 22(2)(3) and article 32(7) of the PIT Act.
Under-26 relief
Employment income of a person who has not turned 26 is exempt from PIT up to PLN 85,528 a year (article 21(1)(148) of the PIT Act). You still pay ZUS and health contributions. At PLN 6,000 gross the yearly income is PLN 72,000, so the tax advance is zero all year. At PLN 10,000 the limit runs out during the year: net pay is PLN 7,852.39 from January to August, PLN 7,719.39 in September (PLN 5,528 is still exempt, tax advance PLN 133), and PLN 7,147.39 from October, the same as without the relief.
PPK
PPK (Pracownicze Plany Kapitałowe) is the workplace savings scheme that employers in Poland run for their staff. The calculator uses the basic contributions: 2% of gross from the employee and 1.5% from the employer (PPK Act, article 27(1) and article 26(1)). On PLN 6,000 that is PLN 120 taken from your net pay. The employer’s PLN 90 counts as taxable income, so the tax base rises to PLN 5,017 and the advance to PLN 302. That explains the PLN 131 difference: PLN 120 contribution plus PLN 11 tax. The calculator always assumes 2% and 1.5%, while the PPK Act allows a lower employee contribution in some cases and additional contributions.
Why net pay changes during the year
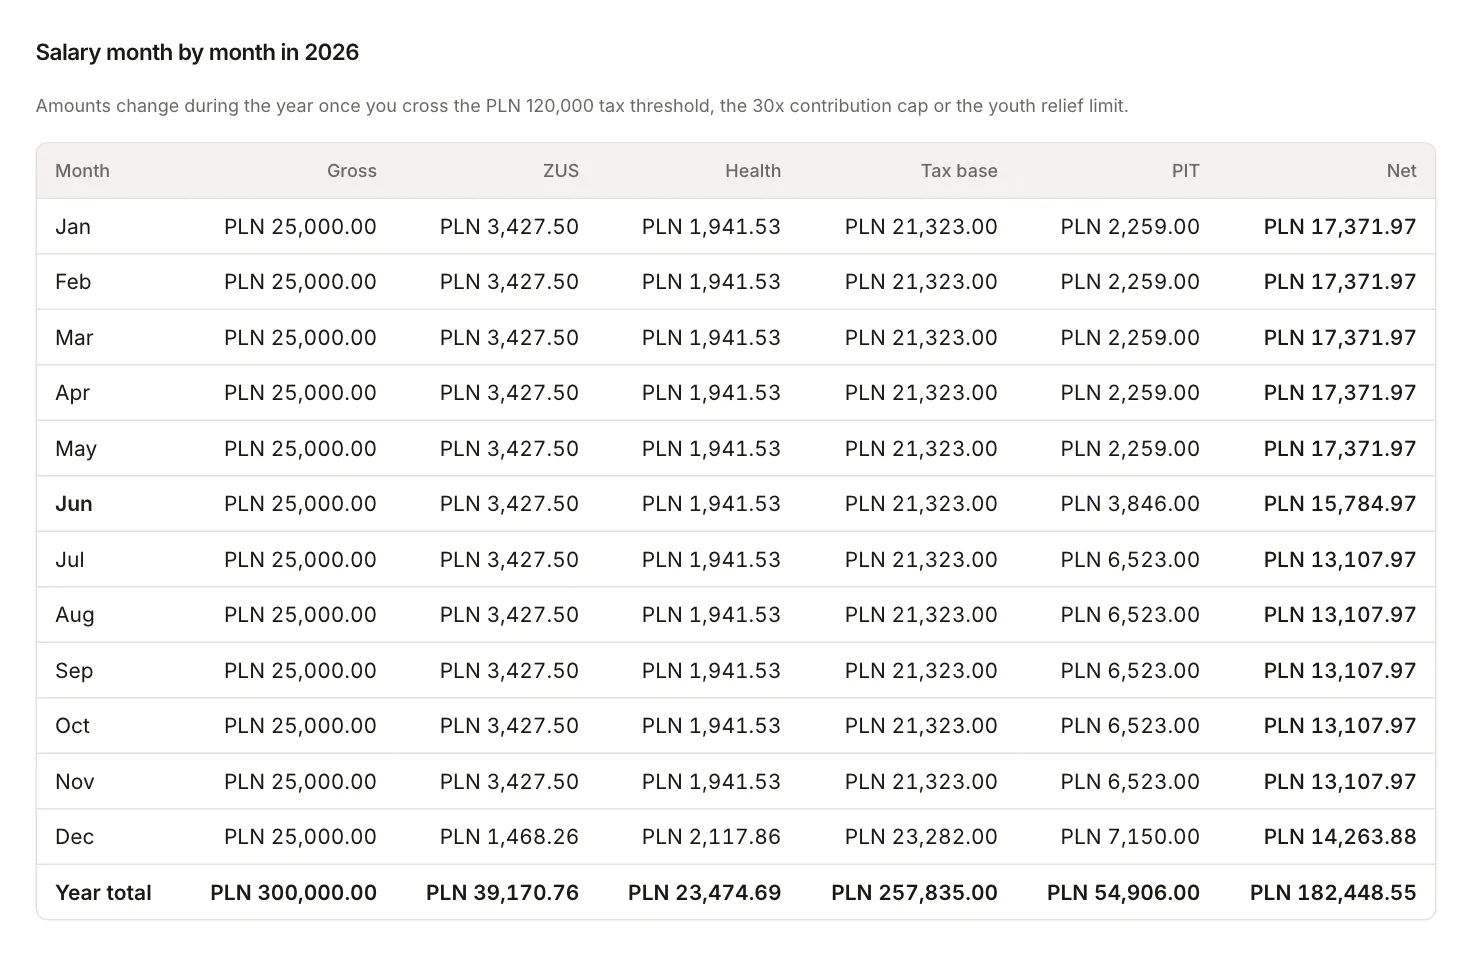
At PLN 6,000 and PLN 10,000 gross (without the under-26 relief) net pay is the same every month. On a higher salary two thresholds, counted cumulatively from January, come into play. The screenshot and calculations below are for PLN 25,000 gross a month, with June selected.
The PLN 120,000 threshold
The advance is 12% of income up to this amount and 32% of the excess. In the month you cross it, both rates apply, and in later months only 32% (article 32(2) of the PIT Act). At PLN 25,000 the monthly tax base is PLN 21,323, so after May the total is PLN 106,615. In June PLN 13,385 is left before the threshold: 13,385 × 12% + 7,938 × 32% - 300 = PLN 3,846.36, rounded to PLN 3,846, so net pay is PLN 15,784.97. From July the advance is 21,323 × 32% - 300 = PLN 6,523 and net pay is PLN 13,107.97. The PLN 300 reduction still applies above the threshold, because it is one twelfth of the annual amount in each of 12 months. Article 31b of the PIT Act does not tie the reduction to the threshold, and the Ministry of Finance confirmed in 2022 that it also applies to people above it. The threshold is counted separately for each payer, so after you change jobs the new employer starts counting from zero.
The 30x contribution cap
In 2026 the annual base for pension and disability contributions is capped at PLN 282,600 (30 × PLN 9,420, notice of the Minister of Family, Labour and Social Policy of 19 November 2025). You do not pay these two contributions on the part above the cap. Sickness and health contributions are charged on the whole salary. After eleven months at PLN 25,000 gross the total is PLN 275,000, so PLN 7,600 is left in December. Pension (PLN 741.76) and disability (PLN 114.00) are calculated only on that amount, and sickness (PLN 612.50) on the full PLN 25,000. Contributions total PLN 1,468.26 instead of PLN 3,427.50. The health contribution rises to PLN 2,117.86 because its base is larger. The tax base is PLN 23,282, the advance is PLN 7,150 and net pay is PLN 14,263.88, which is PLN 1,155.91 more than in November. If you have several employers, the cap applies to the sum of the bases from all of them, and you must tell each payer when you pass it (article 19(6) of the Social Insurance System Act).
In the calculator both messages appear in the month when the threshold is crossed. The “Year total” row for PLN 25,000 shows PLN 182,448.55 net from PLN 300,000 gross.
When you know the net amount and need the gross
Switch the calculator to “Net → gross” and choose a month. The tool looks for the lowest gross salary that gives at least the net amount you entered in that month. For PLN 5,000 net in January (default settings) the answer is PLN 6,850.14 gross. Because net pay changes during the year, the same gross gives a different net in a month after you cross a threshold or the cap.
What the calculator does not cover
- Pay that varies. Bonuses, overtime and sick pay change the monthly amounts, while the calculator assumes 12 equal payments.
- Two jobs or a change of employer during the year. The PLN 120,000 threshold and PIT-2 then work separately with each employer.
- The annual tax return, including child relief and joint filing.
- Exemptions other than the under-26 relief. The PIT Act also exempts up to PLN 85,528 a year of income for people who moved their place of residence to Poland (article 21(1)(152), with conditions) and a few other groups. If that may apply to you, ask your HR or payroll department.
- Tax residency, income from abroad and tax treaties. The calculator applies the Polish scale and Polish social insurance rules to a standard employee.
- Other contract types. Civil-law contracts and self-employment have different contributions and tax. Use the umowa zlecenie calculator or the B2B contract calculator.
Sources and disclaimer
The rates in the calculator (the rates2026.ts file) match the legal acts below. We checked them in October 2026 against the texts from the Journal of Laws and the Official Gazette (Monitor Polski), downloaded from the Sejm ELI API. The acts are published in Polish only.
- Council of Ministers regulation of 11 September 2025 on the minimum wage for 2026 (Dz.U. 2025 item 1242): PLN 4,806 from 1 January 2026.
- Notice of the Minister of Family, Labour and Social Policy of 19 November 2025 (M.P. 2025 item 1206): annual cap of PLN 282,600 for 2026.
- Social Insurance System Act, consolidated text in Dz.U. 2026 item 199: articles 16, 19 and 22.
- Personal Income Tax Act, consolidated text in Dz.U. 2026 item 592: article 21(1)(148), article 22(2), articles 26, 27, 31b and 32.
- Act on publicly funded healthcare benefits, Dz.U. 2025 item 1461: article 79(1), health contribution of 9%.
- Employee Capital Plans Act, consolidated text in Dz.U. 2026 item 192: articles 26 and 27.
- Ministry of Finance: PIT-2 is filed once, 4 January 2022, checked in October 2026.
The amounts in this guide come from the calculator (default settings unless stated otherwise) and match the functions in its code to the grosz, as the script scripts/guide-fixtures/gross-to-net-salary-poland.mjs verifies. The result is for information only and is not legal, tax or financial advice. Your actual payslip depends on what you agreed with your employer, so your HR or payroll department can confirm the final amount.